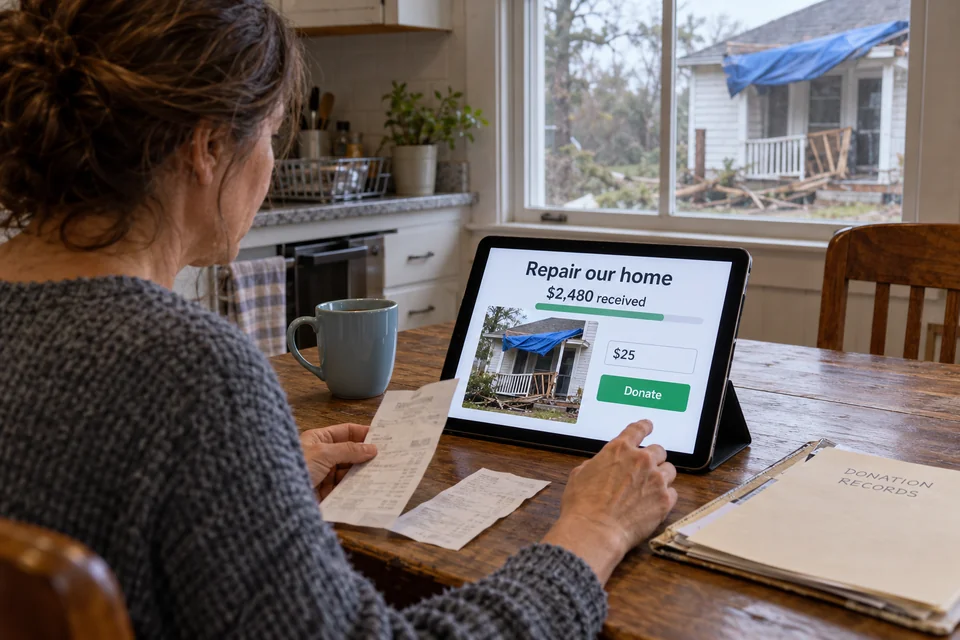
Separate a gift from a taxable receipt or commercial exchange
In the United States, the tax treatment of crowdfunding receipts depends on the facts of the arrangement. The IRS explains that distributions may be included in income and that genuine gifts are assessed differently from payments involving goods, services or a business activity. A campaign’s use of the word donation does not settle the issue. Record who contributed, whether anything was promised in return and whether the organiser received money on behalf of another beneficiary. Review reporting obligations with a qualified adviser when the circumstances are uncertain.[1][2][3][4]
Match the service to a personal or organisational campaign
GoFundMe, Givebutter and GlobalGiving serve different fundraising situations. In its current help guidance, Givebutter supports organisations and affiliated fundraisers rather than standalone personal fundraising accounts; GlobalGiving works with nonprofit projects. Choose a route that matches the actual recipient and document any authority to collect on its behalf. State-level charity solicitation requirements may also matter for organisational appeals, particularly when promotion crosses borders. Explain the intended use of funds without implying that a platform listing certifies a campaign or that every donor receives a charitable deduction.[1][2][3][4]
US fundraising tools and tax guidance
GoFundMe: nonprofit fundraising
Givebutter: eligible users
GlobalGiving: nonprofit model
IRS: crowdfunding tax guidance
Document the character of a US contribution
- Record whether the donor receives any goods or services.
- Identify the recipient separately from the campaign organiser.
- Check applicable tax and charity-solicitation obligations.